How Does a 401(k) Work? 2026 Limits, Match and Withdrawals
Quick answer: A 401(k) is a workplace retirement plan that lets you put pre-tax money (a traditional 401(k)) or after-tax money (a Roth 401(k)) straight from your paycheque into investments the plan offers. For 2026, the IRS set the employee contribution limit at $24,500, or $32,500 if you are 50 or older ($24,500 plus an $8,000 catch-up). People aged 60 to 63 have a higher catch-up, $11,250, under a SECURE 2.0 rule, so they can put in up to $35,750. Many employers also add a matching contribution, which is extra money on top of those employee limits. Withdrawals in retirement are taxed if the contributions were pre-tax; qualified Roth 401(k) withdrawals are tax-free.
If your employer offers a 401(k), it is usually the simplest way to save for retirement, especially when there is a match. The plan can still feel opaque: traditional versus Roth, what happens when you leave a job, and how much you are allowed to put in this year. This guide explains those rules using the IRS figures for 2026. It is general information, not personal tax advice.
How Does a 401(k) Work?
You choose a percentage (or a dollar amount) of your pay to contribute. With a traditional 401(k), that money comes out before income tax, which can lower your taxable pay now; you pay ordinary income tax when you withdraw it in retirement. With a Roth 401(k), you contribute money you have already paid tax on, and qualified withdrawals later can be tax-free. Not every plan offers a Roth option.
The money is invested in the funds your plan lists, often including target-date funds and index funds. You generally cannot take the money out while you are still working, except for narrow cases such as a plan loan or a hardship withdrawal, both of which have strings attached. Employer contributions may follow a vesting schedule, meaning you have to stay for a period before that part is fully yours.
What Are the 401(k) Contribution Limits for 2026?
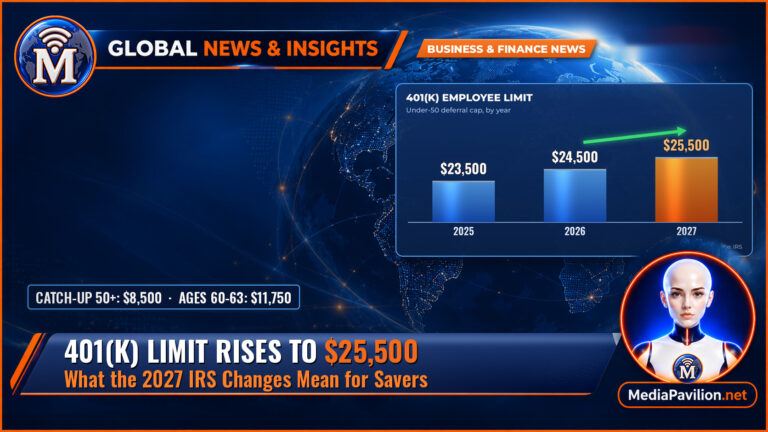
In a 13 November 2025 announcement (IR-2025-111), the IRS raised the employee deferral limit for 401(k), 403(b), governmental 457 plans and the federal Thrift Savings Plan to $24,500, up from $23,500 in 2025. The standard catch-up for employees aged 50 and over rose to $8,000, up from $7,500, for a combined $32,500. Under SECURE 2.0, employees aged 60, 61, 62 and 63 have a higher catch-up of $11,250 in 2026, for a combined $35,750. Those catch-up figures apply to most 401(k)-style plans; SIMPLE plans have different caps.
There is also a wider annual additions limit that covers employee deferrals, employer contributions and some after-tax contributions combined. The IRS publishes that overall cap in the same yearly notice. You can contribute to a 401(k) and an IRA in the same year, but the IRA has its own $7,500 limit for 2026 ($8,600 with the IRA catch-up at age 50-plus). For the difference between Roth and traditional IRAs, see our separate guide to Roth versus traditional IRAs.
What Is an Employer Match, and Should You Take It?
A match is money your employer adds when you contribute, for example 50 per cent or 100 per cent of your deferral up to a set share of your salary. It is usually the closest thing to an immediate, guaranteed return in a retirement plan, which is why many advisers say to contribute at least enough to get the full match before you direct extra savings elsewhere. The match does not reduce your $24,500 employee limit; it sits on top, inside the overall annual additions cap.
Check the vesting schedule. If you leave before you are fully vested, you may keep only part of the employer’s money, though your own contributions are yours.
What Happens When You Leave Your Job?
You typically have several options: leave the money in the old plan if the plan allows it; roll it into a new employer’s 401(k); roll it into an IRA; or cash it out. Cashing out is usually the most expensive path for people under 59½, because it can trigger income tax and a 10 per cent additional tax, with some IRS exceptions. A direct rollover to another retirement account is the cleaner way to keep the tax shelter intact. If you start a new job, compare fees and investment choice before you move the money.
Fees deserve a look once a year. A 401(k) may charge plan administration costs and each fund has an expense ratio. Lower-cost index funds, where available, leave more of your return in the account. You do not need to chase last year’s hottest fund; a simple, diversified mix you will leave alone is usually enough. If the plan’s options are expensive, contributing enough to get the match and putting extra savings in a low-cost IRA can be a reasonable split, depending on your tax situation.
Frequently Asked Questions
Is a 401(k) the same as a pension?
No. A traditional pension (a defined-benefit plan) promises a set income later. A 401(k) is a defined-contribution plan: what you get depends on what was put in and how the investments performed.
Should I choose a traditional or Roth 401(k)?
A traditional plan is often attractive if you expect to be in a lower tax bracket in retirement. A Roth can be attractive if you expect your tax rate to be the same or higher later, or if you want tax-free withdrawals. Some people split contributions. This depends on your own tax position; a tax professional can model it.
What if my employer does not offer a 401(k)?
You can still use an IRA, and some employers offer a SIMPLE or 403(b) instead. Self-employed people may be able to use a SEP IRA or a solo 401(k).
Can I have a 401(k) and an IRA?
Yes. The limits are separate, though your income and workplace coverage can affect whether a traditional IRA contribution is deductible and whether you can contribute to a Roth IRA.
The Bottom Line
A 401(k) takes money from your pay, invests it for retirement, and, if your employer matches, adds free contributions on top. For the 2026 tax year the IRS employee limit is $24,500, or $32,500 from age 50 ($35,750 at ages 60 to 63). Contribute at least enough to collect any employer match, be careful about cashing out when you change jobs, and always use the current official IRS figures rather than last year’s limits. For related retirement and investing basics, see Roth versus traditional IRAs, index funds versus ETFs and the 50/30/20 budget rule.
Related Reading
- Roth IRA vs Traditional IRA: 2026 Limits, Income Rules and Which to Choose
- Index Funds vs ETFs: What’s the Difference and Which Is Better?
- The 50/30/20 Rule: How to Budget Your Paycheck (With Examples)
- Is the Stock Market Open Today? NYSE and Nasdaq Hours, Holidays and Early Closes
Featured image: The New York Stock Exchange on Wall Street, by Arild Vågen / Wikimedia Commons, CC BY-SA 4.0. Cropped, colour-graded and combined with MediaPavilion branding. Image licensed CC BY-SA 4.0.
Sources
- Internal Revenue Service — 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 (13 November 2025).
- Internal Revenue Service — Notice 2025-67, 2026 limitations adjusted as provided in section 415(d) (13 November 2025).
- Internal Revenue Service — Retirement topics – 401(k) and profit-sharing plan contribution limits.